Introduction
Managing money effectively is an important part of building a stable and comfortable future. Whether someone earns a regular salary, runs a business, works independently, or is interested in financial markets, developing good saving habits can make a meaningful difference. Many people understand the importance of saving but struggle to follow a consistent financial routine. Everyday expenses, unexpected bills, lifestyle choices, and financial commitments can make it difficult to set money aside. This is why practical financial education and simple saving strategies are valuable for people at different stages of life.
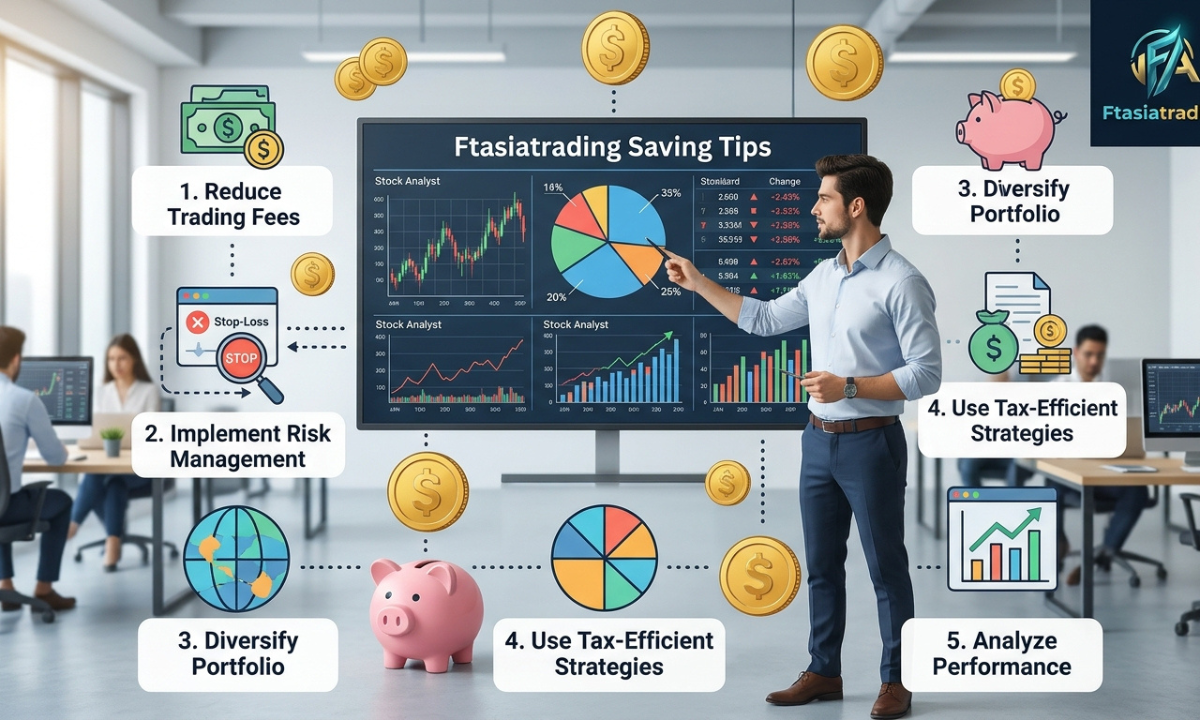
FTAsiaTrading saving tips can be explored as a starting point for understanding how budgeting, financial discipline, and thoughtful decision-making contribute to better money management. Saving is not simply about spending less; it is about using available resources wisely and preparing for future needs. By creating realistic goals, monitoring expenses, and developing consistent habits, individuals can gradually improve their financial position. A well-organized approach to saving can also provide greater confidence when dealing with unexpected situations and long-term financial responsibilities.
Understanding the Importance of Saving Money
Saving money provides financial security and creates opportunities for future growth. Without savings, even a relatively small unexpected expense can create stress. Medical bills, vehicle repairs, household emergencies, and temporary income interruptions are examples of situations where having accessible funds becomes important. Regular saving helps individuals prepare for these circumstances instead of relying entirely on borrowed money or credit.
Another important advantage of saving is the ability to work toward personal goals. People may want to purchase a home, continue their education, start a business, travel, or prepare for retirement. These goals often require financial preparation over several months or years. Developing a saving routine makes large expenses more manageable because money is accumulated gradually rather than collected at the last moment.
Creating a Practical Monthly Budget
A monthly budget is one of the most effective tools for controlling personal finances. It helps individuals understand how much money they receive, where their income goes, and how much they can reasonably save. Without a budget, small purchases can become difficult to track, eventually reducing the amount available for important financial priorities.
The first step is to calculate total monthly income. This includes salary, business earnings, freelance payments, and other regular sources of income. Next, list essential expenses such as rent, groceries, transportation, electricity, education, and loan repayments. After identifying these costs, calculate the amount remaining for savings and optional spending.
FTAsiaTrading saving tips encourage readers to consider budgeting as an ongoing habit rather than a one-time activity. A budget should be reviewed regularly because income and expenses can change. Even a simple notebook or spreadsheet can help maintain financial awareness and prevent unnecessary spending.
Setting Clear and Achievable Saving Goals
Saving becomes easier when individuals know exactly why they are putting money aside. General intentions such as wanting to become financially successful may not provide enough motivation to maintain consistent habits. Specific goals offer a clearer direction and make progress easier to measure.
For example, someone might decide to save money for an emergency fund, a new laptop, higher education, or a future property purchase. Each goal should have a target amount and an estimated completion date. Breaking a large target into smaller monthly contributions can make the process less intimidating.
It is also useful to divide goals into three categories: short-term, medium-term, and long-term. Short-term goals may involve saving for a small purchase, while medium-term goals could include education or business development. Long-term goals may involve retirement planning or purchasing property. This structure helps people organize their priorities and allocate money more effectively.
Developing the Habit of Paying Yourself First
One common financial mistake is waiting until the end of the month to save whatever money remains. In many cases, little or nothing is left because everyday expenses gradually consume the available income. Paying yourself first offers a different approach.
This strategy involves transferring a predetermined amount into savings immediately after receiving income. The remaining money can then be used for necessary expenses and planned purchases. Even a small contribution can become meaningful when repeated consistently over time.
For example, an individual who saves ₹2,000 every month will accumulate ₹24,000 over twelve months, excluding any interest. Someone who can save ₹5,000 monthly will accumulate ₹60,000 during the same period. These examples demonstrate how regular contributions can produce noticeable results without requiring a dramatic lifestyle change.
Reducing Unnecessary Everyday Expenses
Everyday spending decisions have a significant influence on personal savings. Small purchases may appear inexpensive individually, but repeated expenses can create a considerable financial burden. Ordering food frequently, purchasing unused subscriptions, shopping without a plan, and buying products simply because they are discounted are common examples.
Reducing unnecessary expenses does not mean avoiding everything enjoyable. Instead, it means identifying purchases that provide little value and adjusting spending accordingly. Preparing meals at home, comparing prices, using existing household items, and planning shopping trips can help reduce monthly costs.
Another useful method is the 24-hour purchasing rule. Before buying a non-essential item, wait for one day and reconsider whether the purchase is genuinely necessary. This simple practice can reduce impulse buying and encourage more thoughtful decisions.
Building an Emergency Savings Fund
An emergency fund is an important part of a healthy financial plan. It provides money for unexpected situations without disturbing regular household finances or long-term savings goals. Many financial planners recommend gradually building an emergency reserve equivalent to three to six months of essential living expenses, although the appropriate amount depends on individual circumstances.
People who are just beginning their savings journey do not need to achieve this target immediately. They can start with a smaller amount, such as ₹5,000 or ₹10,000, and increase it over time. The most important factor is consistency.
FTAsiaTrading saving tips highlight the importance of separating emergency savings from everyday spending money. Keeping this fund in an accessible savings account can make it easier to use when necessary while reducing the temptation to spend it on non-essential purchases.
Understanding the Difference Between Saving and Investing
Saving and investing are related financial activities, but they serve different purposes. Saving generally involves keeping money in relatively accessible and lower-risk financial products for future expenses. Investing involves putting money into assets with the expectation of potential growth, although returns are uncertain and losses are possible.
Savings are generally more appropriate for emergency funds, upcoming bills, and short-term financial goals. Investments may be considered for longer-term objectives when individuals understand the risks involved and have sufficient financial stability.
It is important not to invest money that may be needed immediately. Financial markets can experience fluctuations, and investments may lose value. Before making investment decisions, individuals should understand their risk tolerance, investment timeline, and financial responsibilities.
Avoiding Unnecessary Debt
Debt can make saving more difficult, particularly when individuals carry high-interest credit card balances or repeatedly borrow money for non-essential purchases. Interest payments reduce the amount of income available for savings and other financial priorities.
The first step toward managing debt is creating a complete list of outstanding balances, interest rates, and minimum payment requirements. This information helps individuals understand which obligations require attention.
Two common repayment strategies are the debt avalanche and debt snowball methods. The avalanche method prioritizes debts with the highest interest rates, potentially reducing total interest costs. The snowball method focuses on paying off smaller balances first, which may provide motivation through visible progress.
Avoiding unnecessary borrowing and making payments on time can support a more stable financial position.
Using Technology to Track Financial Progress
Digital tools have made personal money management more convenient. Budgeting applications, banking services, expense trackers, and spreadsheets allow individuals to monitor transactions and understand spending patterns.
A simple expense-tracking system can reveal where money is being used. For example, someone may discover that transportation, online shopping, or food delivery represents a larger portion of monthly spending than expected. Recognizing these patterns makes it easier to identify areas for improvement.
Technology can also support automatic savings transfers. Setting up a recurring transfer after payday reduces the need to remember every contribution manually. However, users should choose secure financial applications, protect their account credentials, and regularly review transactions.
Practicing Smart Shopping Habits
Shopping decisions can influence financial stability more than people realize. Purchasing products without comparing prices or checking quality may result in unnecessary expenses. Smart shopping involves understanding personal needs and choosing products that provide genuine value.
Before making a purchase, compare prices across different sellers and consider product durability, maintenance costs, and warranty conditions. Buying something inexpensive is not always the most economical decision if it needs frequent replacement.
Creating a shopping list before visiting a store can also prevent unplanned purchases. For larger expenses, researching alternatives and waiting for an appropriate opportunity may help individuals avoid financial pressure. These habits encourage responsible spending without sacrificing essential needs.
Maintaining Financial Discipline Over Time
Financial improvement requires patience and consistency. Some months may bring unexpected expenses, reduced income, or other challenges that make saving difficult. These situations should not automatically be considered failures. Instead, individuals can adjust their budgets and return to their saving routines when circumstances improve.
Reviewing financial progress every month can help identify achievements and areas that need attention. If a particular saving target is too difficult, reducing the monthly contribution temporarily may be more practical than abandoning the goal completely.
FTAsiaTrading saving tips also emphasize the value of financial awareness. Learning about budgeting, interest rates, inflation, debt management, and investment risks can improve everyday financial decisions. Better knowledge allows individuals to approach money matters with greater confidence.
Common Saving Mistakes to Avoid
Even people with good intentions can make mistakes that slow down financial progress. One common problem is setting unrealistic saving targets. Attempting to save too much at once can create pressure and make it difficult to maintain the habit.
Another mistake is ignoring inflation and the changing cost of living. Financial plans should be reviewed periodically to ensure that saving goals remain realistic. Keeping all financial resources in one place without considering accessibility and safety can also create problems.
People should avoid making financial decisions based entirely on social media recommendations or promises of unusually high returns. No legitimate investment can guarantee high profits without risk. Research, careful planning, and an understanding of personal financial circumstances are essential before committing money.
The Role of Long-Term Financial Planning
Long-term financial planning connects everyday saving habits with larger life objectives. It involves considering future responsibilities such as education, homeownership, family expenses, healthcare, and retirement.
A useful financial plan should reflect personal income, current obligations, and expected future needs. Individuals can review their plans annually and make adjustments when their circumstances change. For example, a salary increase may provide an opportunity to increase monthly savings rather than immediately increasing lifestyle expenses.
FTAsiaTrading saving tips can serve as a reminder that financial success is generally built through a combination of informed decisions, disciplined spending, and realistic expectations. There is no universal strategy that works equally well for everyone. The most effective plan is one that individuals can maintain according to their financial situation.
Conclusion
Developing strong saving habits is an important step toward financial stability and greater independence. A practical budget, clear financial goals, regular contributions, emergency savings, and responsible spending can help individuals manage their money more effectively. These habits do not require a high income or complicated financial strategies. They require awareness, patience, and a willingness to make consistent improvements.
FTAsiaTrading saving tips provide a useful topic for exploring the relationship between everyday financial decisions and long-term financial well-being. By understanding the difference between saving and investing, managing debt carefully, and avoiding unnecessary purchases, individuals can create a stronger financial foundation. Ultimately, successful money management is not about becoming wealthy overnight. It is about making thoughtful choices today that support a more secure and financially prepared future.